Managing earnings from driving or delivery work can become surprisingly complicated once a shift ends. Money may arrive at different times, spending can happen from several accounts, and a small access problem can interrupt an otherwise simple routine. I spent time looking at Uber Pro Card as a finance app built around that kind of work, and my impression is that its value depends less on flashy tools than on whether it fits the way you already receive and use your earnings.
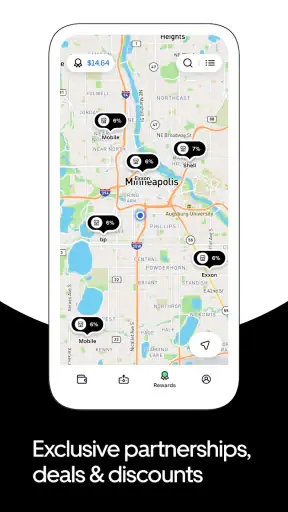
The app is developed by Branch Messenger and is free to use, with an Everyone age rating. Its store summary, “Keep more of what you earn,” points to its central purpose: giving eligible Uber workers a dedicated way to manage work-related earnings rather than treating every payment as part of a general banking setup. That focus is useful, but it also means this is not automatically the best choice for somebody looking for a broad personal-finance replacement.
I found the strongest case for it among people who want a clear separation between gig-work income and household money. If you drive or deliver regularly, keeping those earnings in a dedicated place can make it easier to see what the work is actually producing. If you only use Uber occasionally, however, the extra account and app may feel like another item to monitor rather than a meaningful improvement.
Where the real friction tends to appear
The first surprise for many users is that installing a finance app is only one part of getting started. The important question is whether the account, work activity, and identity details line up well enough for the service to recognize the user. When something goes wrong, people often blame the app immediately, even though the problem may be an incomplete profile, a mismatch in personal details, or an issue with the connected work account.
That is why I would approach the first launch slowly. I would use the same personal information associated with my Uber work profile, check every character before submitting it, and avoid switching repeatedly between accounts during setup. A rushed registration can create confusion later, especially when trying to understand whether a delay concerns access, earnings, or the payment destination itself.
Another common sticking point is expecting every payment to behave like a normal bank transfer. Work earnings can follow their own timing and eligibility rules, while the app is only one part of the overall chain. If a balance does not look right immediately after a shift, I would first compare the completed work shown in the Uber side of the experience with the amount visible in the card account. That simple comparison helps identify whether the issue began before the money reached the app.
The most useful habit is to separate an account-access problem from an earnings-timing problem. They can look similar on screen, but the next step is different. Repeatedly reinstalling the app will not solve a payment that has not yet been sent, and waiting for a payment will not fix a sign-in problem.
What I would check before blaming the app
I would begin with the basics: a stable internet connection, the correct login details, and the latest available version installed on the phone. Uber Pro Card is currently listed as version 2026.8.2 and requires Android 10 or later, so an older Android device can be a practical limitation before any account troubleshooting begins. On iOS, I would likewise keep the operating system and app current, because outdated software can create odd loading or authentication behavior.
I would also make sure the phone has enough free storage and that automatic date and time settings are enabled. These checks sound ordinary, but finance apps rely on secure connections and accurate session information. A device with an incorrect clock or an unstable connection may appear to have an account failure when the underlying issue is local to the phone.
For a new user, I would avoid setting up the account while moving between weak mobile coverage and public Wi-Fi. A registration step that stops halfway can leave the user unsure whether it completed. A better approach is to wait for a reliable connection, finish one screen at a time, and take note of the exact point where the process stops. That detail is much more useful than simply reporting that “the app does not work.”
Notifications deserve a practical check too. If the app is meant to help you notice earnings or account activity, blocked notifications can make it seem unresponsive even when the account is functioning. I would review the phone’s notification settings, battery restrictions, and background activity controls before assuming that updates are missing. The wording and menu names vary by device, but the principle is the same: an app cannot alert you if the operating system is preventing it from running normally in the background.
Making the first workday easier to audit
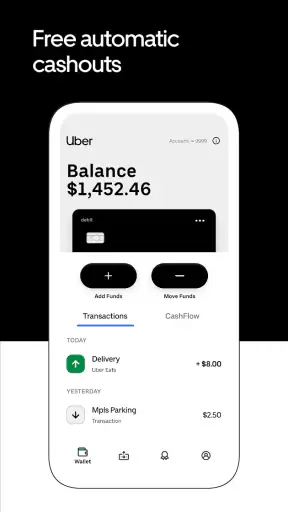
My preferred setup would be to use the app as a dedicated work-money checkpoint rather than constantly opening it during a shift. Before starting work, I would confirm that I can sign in. After finishing, I would compare the earnings record with the balance or activity shown in the card account. This creates a simple two-step audit without turning every delivery into a financial interruption.
That workflow also helps with budgeting. Instead of treating the full balance as spendable, I would decide in advance which portion is reserved for fuel, maintenance, taxes, or personal spending. The app may help keep the money organized, but it cannot replace the user’s own plan. A dedicated work account is most useful when it supports a routine rather than becoming another place where money disappears from view.
One less obvious advantage of this separation is emotional clarity. Gig income can look generous on a busy day while hiding the costs of producing it. Reviewing the balance separately from a main checking account makes it easier to ask whether a shift was genuinely worthwhile. I would not use the app alone to calculate profit, but I would use it as one part of that calculation.
There is also a trade-off. A separate card and app can reduce clutter in a personal account, yet it can create more places to check. If you already have a reliable method for receiving Uber earnings, moving money between accounts may add steps without improving your decisions. The dedicated setup is most convincing for someone who values separation and quick visibility more than having everything under one traditional bank login.
Recovering when a normal workflow breaks
When the app behaves unexpectedly, I would use a calm recovery sequence rather than trying several changes at once. First, I would close and reopen it, then check the connection and sign in again. If the problem continues, I would restart the phone and confirm that the app and operating system meet their requirements. These actions are basic, but changing one variable at a time makes it easier to tell what helped.
If the app opens but information looks incomplete, I would record what is visible: the last successful activity, the time of the missing item, and whether the Uber work record shows the same event. I would avoid making a financial decision based on a balance that appears stale. For example, I would not assume that a missing update means the money vanished, and I would not spend against an amount that has not clearly appeared.
For sign-in trouble, I would use the account-recovery path presented inside the app and follow it carefully instead of creating a second account. Multiple accounts can make later verification more confusing. I would also avoid sharing passwords, security codes, or sensitive account information with anyone offering unofficial help. Finance-related troubleshooting should stay inside the app’s recognized support process and the official Uber or Branch Messenger channels available to the user.
When a payment appears delayed, the most useful evidence is a timeline. I would note when the work was completed, when Uber marked the earnings as available, and when the card account last updated. This is more informative than checking the same screen repeatedly. If the Uber record itself has not finalized, the card app is unlikely to be the place where the delay began.
Clearing an app cache can sometimes help with a stuck screen on Android, but I would treat it as a later step and make sure I understand what information is stored locally before doing anything more drastic. I would not erase app data or uninstall the app during an unresolved account issue unless I knew I could sign back in and had another way to keep track of pending activity. A clean reinstall is not always a clean solution for a finance account.
When the problem is outside the app
It is important to distinguish a display problem from a real payment problem. If the Uber work history and the card account disagree, the correct support route may depend on which side contains the error. A missing trip or delivery in the work record points toward the Uber workflow. A completed earning that is recognized there but not reflected in the card account points toward the payment or account-support workflow. Knowing that difference can save a great deal of back-and-forth.
Phone-level issues can also be misleading. A full inbox, aggressive battery saver, disabled notifications, poor coverage, or an outdated operating system can all make a working account feel unreliable. I would test the app on a stable connection and check whether other apps have the same network problem. If several services are failing, the card app is probably not the root cause.
There is a similar distinction between an account limitation and an app bug. If the app clearly displays a message about eligibility, verification, or account status, reinstalling it will not change that decision. The sensible response is to read the message closely, keep any reference information, and contact the relevant official support channel. I would never try to bypass an account check by changing personal details or opening duplicate profiles.
Privacy is another reason to keep troubleshooting disciplined. I would not send screenshots showing full card numbers, security codes, or unnecessary personal information. If a screenshot is needed, I would hide sensitive details first. This is a small but important part of using any finance app safely, especially when seeking help in a public forum or from an unfamiliar person.
How it compares with ordinary alternatives
Compared with a traditional bank account, Uber Pro Card has a narrower purpose. A normal bank is usually better for managing rent, savings, bills, and several income sources in one place. It may also be more familiar to people who want branches, broader account products, or a long-term household banking relationship. I would choose that route if my main goal were general money management rather than handling Uber earnings separately.
Compared with a prepaid card or a general budgeting app, this service is more closely connected to the working pattern of Uber drivers and couriers. That focus can reduce the effort of mentally sorting work income from personal money. The trade-off is flexibility: a general budgeting tool may provide a wider view across accounts, while a dedicated card experience may require you to maintain a separate routine.
Compared with simply receiving earnings in an existing checking account, the choice comes down to control and convenience. Keeping everything together is easier and may avoid transfers or extra monitoring. Using a separate work-focused account can make earnings easier to review and protect them from being mixed with everyday spending. Neither option is universally better. I would decide based on whether separation changes my behavior for the better.
The app’s strong public reception is notable: it has a 4.9 average from around 82 thousand ratings, with more than a million installs. Those figures suggest that many users find the basic experience worthwhile, but they should not replace personal testing. A highly rated finance app can still be a poor fit for someone whose preferred bank already handles gig income cleanly or who dislikes maintaining a second financial destination.
Who should use it, and who should skip it
I would recommend giving Uber Pro Card a serious look if you earn from Uber consistently, want a dedicated place for that money, and are willing to check both the work record and the card account when something seems delayed. It is especially practical for people who want to build a habit around separating gross gig earnings from personal spending.
I would be more cautious if your Uber activity is occasional, your existing bank already gives you clear income tracking, or you need one app to manage a complete household budget. I would also skip it if you are uncomfortable with account verification steps or do not want to troubleshoot the connection between a work platform and a finance service. The app cannot remove every layer of that relationship.
For everyday use, my advice is to start with a small, predictable routine: verify access before a shift, review the completed work afterward, and avoid spending money that has not clearly settled. Keep a separate record for business costs and taxes, because a card balance is not the same thing as profit. That workflow extracts the most useful part of the app without asking it to do a job it was not designed to do.
My practical verdict after weighing the trade-offs
Uber Pro Card makes sense as a focused finance tool for Uber workers who want their earnings handled separately from ordinary personal banking. I like the idea of using it as a dedicated checkpoint for gig income, and the free price removes one obvious barrier to trying that approach. The developer is Branch Messenger, the app is rated for Everyone, and its broad availability makes it approachable for many users with compatible devices.
Still, I would not describe it as a universal banking answer. The main friction is not necessarily the screen design; it is understanding where an issue begins when work activity, account status, payment timing, phone settings, and connectivity all meet. Users who keep that distinction in mind will have a much easier experience than those who expect every missing update to be solved by reinstalling the app.
My final recommendation is conditional but positive: try it if separating Uber earnings would genuinely improve your routine, and judge it after a few complete work-and-review cycles rather than after the first login. If it makes income easier to track without adding confusing extra steps, it is a useful companion. If your current bank already gives you the same clarity, staying with that simpler arrangement may be the better decision. Its real strength is focused organization, not replacing every financial tool you already use.


